
Transferring real estate, company shares or other valuable assets to children can be an effective way to organize family wealth and plan for the next generation. However, high-net-worth families often overlook a practical problem: the recipient may receive valuable assets without having enough cash to pay the applicable gift tax.
This is particularly common when parents donate shares in a family holding company or interests in real estate investment companies. Their children may become owners of substantial assets, but those assets do not necessarily provide the immediate liquidity required to meet their tax obligations.
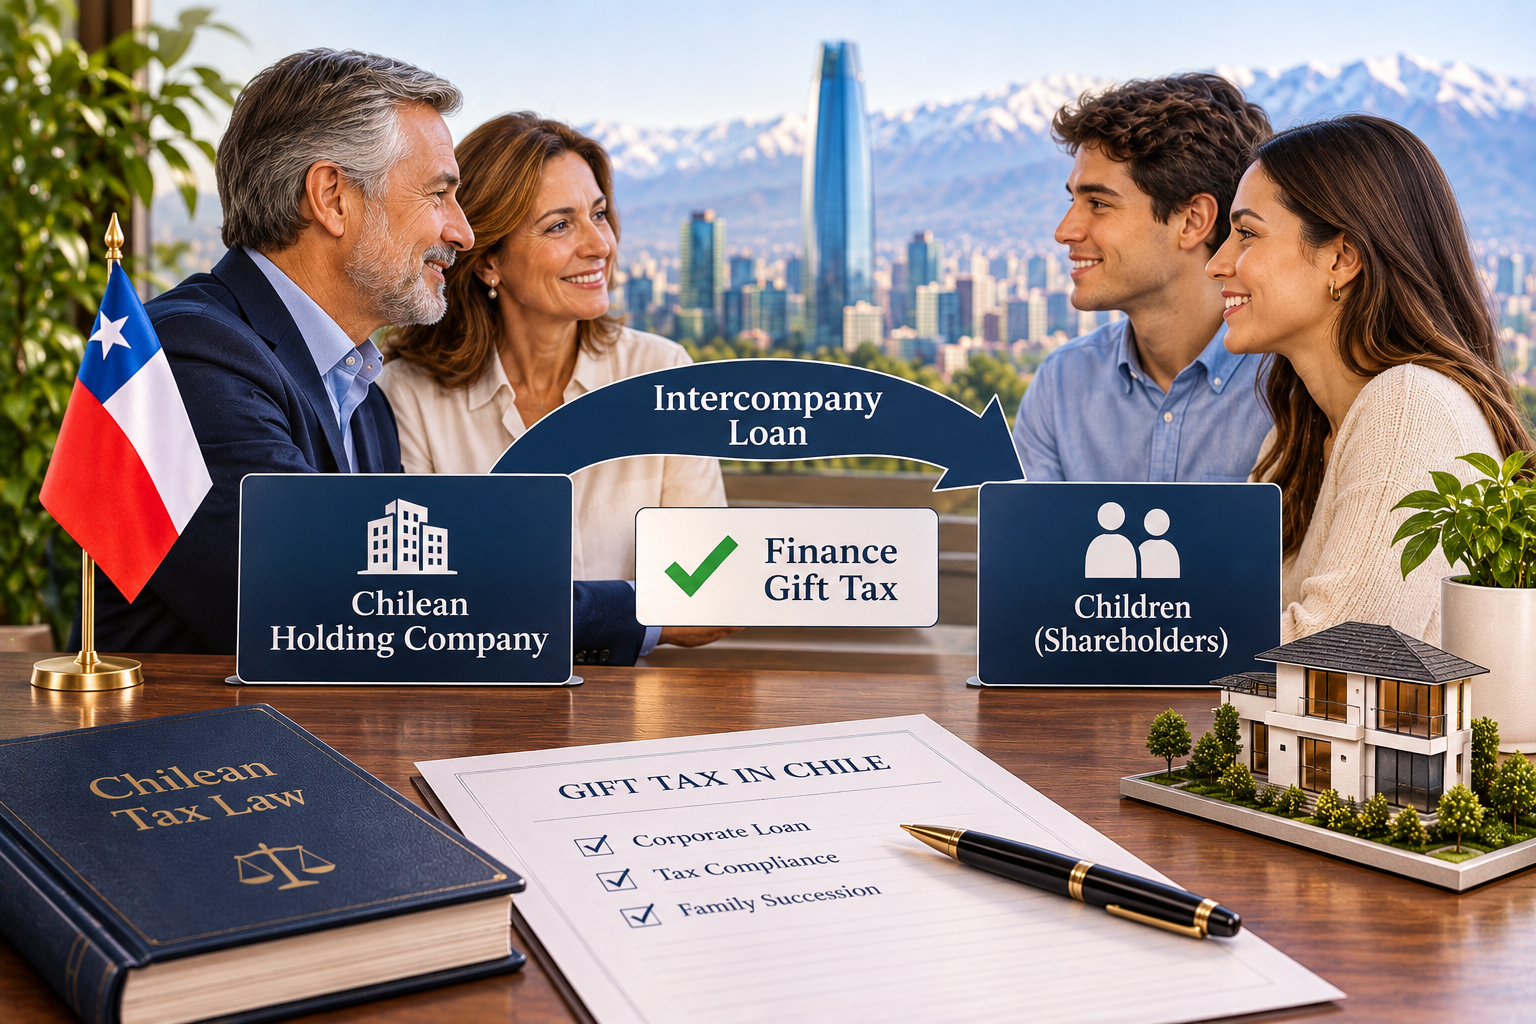
Chile’s Law No. 21,850, published on October 17, 2026, introduces a temporary tax benefit that also provides a specific financing mechanism. Under certain conditions, the recipient can finance the gift tax through loans granted by the company whose shares or ownership interests are being donated, or by another related company.
For families with Chilean corporate structures, this can offer a way to coordinate asset transfers and liquidity planning.
The legal framework: related-company loans to finance gift tax
The first transitional article of Law No. 21,850 establishes a one-time 50% reduction in the gift tax for qualifying donations made during the statutory period.
It also expressly allows the recipient (donatario) to finance the applicable gift tax through:
- Loans (mutuos) granted by public deed.
- Promissory notes authorized before a notary.
The funds must come from companies whose shares or ownership interests are being donated, or from other related companies.
The law specifically provides that qualifying loans are not subject to the taxation established under Article 21 of the Chilean Income Tax Law. This is important because Article 21 may impose additional tax consequences on certain company loans or benefits granted to shareholders or related parties.
However, this is a specific statutory exception, not a general exemption for every loan between family members or related companies.
Which donations qualify for the 50% tax reduction?
The financing mechanism must be considered together with the requirements for the temporary gift tax benefit.
The main conditions include:
Eligible recipients. The reduction is generally available to the donor’s potential forced heirs (legitimarios) and beneficiaries of the fourth of improvements under Chilean succession law. Donations to other recipients qualify only if the donor has no such beneficiaries at the time of the donation.
A 50% limit on the donor’s estate. The total value of donations benefiting from the regime cannot exceed 50% of the donor’s total net estate. This is calculated by subtracting documented liabilities from assets valued under the applicable rules of Law No. 16,271.
Minimum remaining assets. The donor must demonstrate that they own assets worth at least twice the amount donated.
A sworn declaration. The donor must declare the relevant family relationships, allocation of donated amounts and compliance with the statutory asset requirements. This declaration must be submitted to the Chilean Internal Revenue Service (SII), together with the supporting documentation required by its instructions.
These conditions are essential. A donation does not qualify merely because it is made between parents and children.
How the corporate financing structure works
Consider a family that owns a Chilean holding company with a portfolio of real estate investments.
The parents decide to donate shares in that company to their adult children. The donation meets the requirements of Law No. 21,850, but the children do not have sufficient personal liquidity to pay the resulting gift tax.
A possible structure would work as follows:
- The parents assess their estate and determine whether the proposed donation meets the statutory limits.
- The donation is formalized through a public deed within the applicable one-year period.
- The gift tax is calculated, applying the 50% reduction if all requirements are met.
- The holding company, or another qualifying related company, grants the children a loan to finance the tax.
- The loan is documented through a public deed or a promissory note authorized before a notary, expressed at least in UF and with a repayment term not exceeding ten years.
- The children use the funds to pay the gift tax and repay the company according to the agreed terms.
This arrangement can help the children receive family assets without having to sell investments or real estate simply to obtain the cash needed to pay the tax.
Loan requirements and tax limitations
The statutory exception from Article 21 taxation depends on compliance with specific conditions.
The loan or promissory note must:
- Be granted by an eligible company.
- Be formalized through one of the instruments expressly permitted by law.
- Be denominated at least in Unidades de Fomento (UF).
- Have a maximum repayment term of ten years from the date the loan is granted.
If these minimum requirements are not met, the special exclusion from Article 21 taxation does not apply.
There is also an important limitation: if the lending company borrows money to finance the loan to the recipient, the interest associated with that borrowing is not deductible as a business expense under the special provision.
Furthermore, the Article 21 exception does not automatically exempt the loan from Stamp and Stamp Tax or other applicable obligations. These must be reviewed separately.
Timing matters: the temporary regime
Law No. 21,850 was published on October 17, 2026. The one-year period for executing qualifying donations begins on December 1, 2026.
The donor must also submit the required sworn declaration within the statutory period. The public deed, tax filing, payment and supporting documentation must be coordinated to comply with the procedure established by law and the SII.
For families considering this strategy, preparation should begin before the donation is executed.
Plan the donation and financing together
The corporate loan mechanism can be useful for families transferring substantial assets to their children, particularly when the recipients lack personal liquidity. However, its effectiveness depends on the eligibility of the donation, the donor’s financial position, the relationship between the companies and the proper documentation of the loan.
A careful review should consider the holding company’s structure, the valuation of the assets, the donor’s net estate, the recipients’ legal status and the tax consequences of the financing.
Finance your heirs’ tax obligations through properly structured corporate loans, using the specific exception provided under Chilean law. Contact Becker Abogados to review your family’s corporate structure and plan your asset transfers in compliance with Law No. 21,850.
Recent Comments